

Ask a founder how the company is doing and you’ll hear about the round. Who’s interested, who stopped replying, what the term sheet says. Ask how many months of cash are left and there’s often a pause while they go and find the spreadsheet.
I’d rather see a weak pitch deck than that pause. A bad investor meeting is recoverable. Finding out in month ten that you can cover two more salaries usually isn’t.
In this article, we’ll deals with both sides of startup funding in India: getting the money, and not wasting it once it lands. Plus, keep in mind that “schemes” and “tax rules” change often, so check anything below against the official source before you rely on it.
[Author: add 2 to 3 lines here from your own experience, such as a round you raised, a cash crunch you watched up close, or a mistake you made. It’s the single best way to make this piece sound like you.]
How do funding stages work in India?
Each stage exists to answer one question.
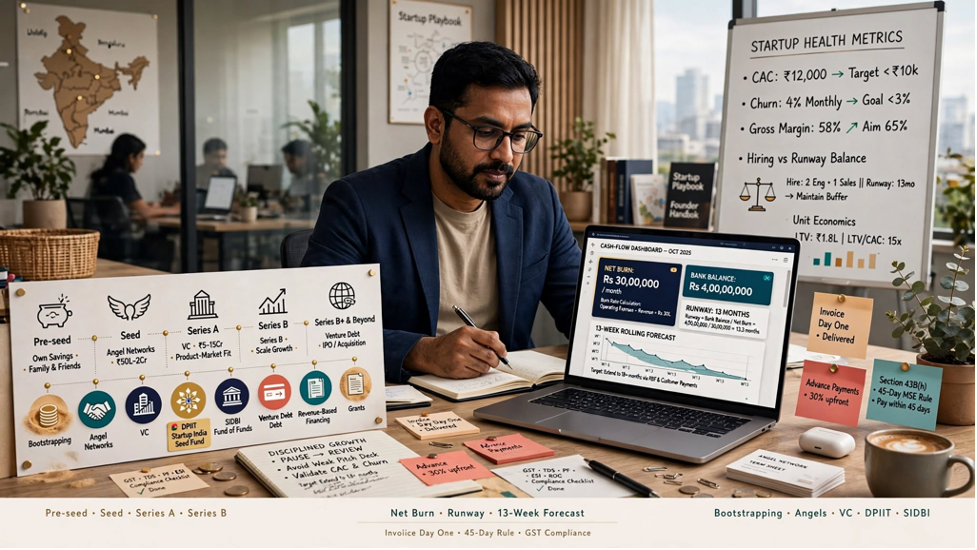
Pre-seed is you, your savings, maybe some money from family. The question is whether you can build something real enough to put in front of people.
Seed is usually the first outside money. It covers a small team and a product that customers actually use. At this stage, investors are mostly betting on the founders because there isn’t much else to judge. Be ready to explain why you’re the right person for this business and why you’re starting it now.
At Series A the questions get sharper. Investors look for a repeatable way of winning customers, revenue that climbs month after month, and some sign that the business gets stronger as it grows. Series B and later is scaling something that already works, into new cities, new products, sometimes new countries.
Round sizes change a lot by sector and by year, so I’m not going to quote figures that will be stale in six months. Look at what companies like yours raised recently instead. The funding tracker on Malik Times lists recent deals, investors and amounts, and ten minutes there will tell you more than a friend’s story about a round raised in a different market.
Where does the money come from?
Your customers, first. Bootstrapping gets little attention in India, but if people will pay you early you keep control and find out what the business is worth before anyone else decides for you.
Angel investors put in their own money, and many are former founders or senior executives. Angel networks have made them easier to meet. A good one gives you more than the cheque: an introduction to your first large client, or a straight answer when your pricing is off.
Venture capital works on a logic that founders often miss until it’s too late. A VC fund needs a few enormous outcomes to make the whole fund work, so it wants companies that can become very large. If yours can, good. If you’re building a solid, profitable business that will stay mid-sized, VC money will push you toward risks and growth rates that don’t suit you. Plenty of decent companies have been hurt by capital they never needed.
Government routes come next. With DPIIT recognition under Startup India, a few doors open. The Startup India Seed Fund Scheme provides funding through approved incubators to help startups build prototypes and enter the market. SIDBI’s Fund of Funds for Startups works differently. It invests in venture funds, which then invest in startups. There is also a credit guarantee scheme that helps startups get loans without putting up heavy collateral.
Expect forms and waiting. I wouldn’t build a hiring plan around any of it, but if you qualify, it’s money that costs you no equity.
Venture debt and “revenue-based financing” suit businesses with steady income. They go badly when revenue lurches from month to month, because repayments arrive on schedule whatever kind of quarter you had.
One piece of old advice you can drop: the angel tax. It treated investment above a “fair” valuation as income, and founders feared it for years. The 2024 Union Budget abolished it. If an article tells you to plan around it, check its date.
How should you think about valuation?
Early valuation is a negotiation. Nothing in a textbook tells you what a company with thin revenue is worth, so what you’re settling is how much of the business you sell for how much money.
At seed, founders often sell somewhere between 15 and 25 percent, though it moves around. The mistake I see most is chasing the highest number while ignoring the terms under it. A slightly lower valuation with clean terms usually beats a flashy one carrying a heavy liquidation preference that bites two rounds later.
A very high valuation also sets a bar you have to clear. Raise at a rich price, grow slower than planned, and the next round may come in lower. That hurts everyone, and it’s hard on a team’s morale. Take the price you can grow into.
What is your runway, really?
Burn rate is what you spend each month. Net burn is that figure minus what customers pay you. Runway is your cash divided by net burn, which gives you the months you have left.
Suppose you hold ₹4 crore, spend ₹45 lakh a month and collect ₹15 lakh. Net burn is ₹30 lakh, so you have about 13 months.
Now imagine a bad month. A big client pays 45 days late and sales come in 20 percent under plan. Where does 13 months go? If it’s nine, you’d rather learn that from a spreadsheet now than from your bank balance later.
It matters for fundraising because the process drags. Three to six months from first meeting to money in the account is normal. Start with nine months of cash and you can turn down a poor offer. Start with three and every investor can see the clock, and the terms tend to reflect it.
Cash flow problems that hit Indian startups harder
Late payment is the big one. Enterprise customers often take 60, 90, sometimes 120 days to clear an invoice, while your team expects salary on the last working day. A few months of that can leave a growing company short.
There’s a rule you should know about. Under “Section 43B(h)” of the “Income Tax Act”, a buyer can claim a deduction for amounts owed to micro and small enterprises only in the year they actually pay, and payment is expected within 45 days with a written agreement or 15 days without one. It applies if your startup is registered as a micro or small enterprise and sells to larger buyers. It’s a concrete thing to mention when you’re chasing a slow payer. Ask your CA how it applies to you.
Compliance is the cost people forget to budget. GST returns, TDS, PF, ESI and ROC filings still “need to be done” on time — even when business is slow. If you “file lately”, it can lead to penalties, and investors may question your records during due diligence.
What helps in practice:
- Invoice on the day you deliver, not at month-end.
- Ask new clients for an advance or milestone payments, especially the big ones.
- Keep a rolling 13-week cash forecast and update it every Monday. It’s a plain sheet of expected money in and out, week by week, and it shows a shortfall weeks before it arrives.
Interest rates, consumer demand and input costs eventually reach your numbers as well, so I’d read general business news next to your own figures.
How do you get ready to raise?
Investors fund evidence, so bring some. Know your “monthly revenue”, growth rate, customer acquisition cost, churn and gross margin by heart. Having to search for these numbers during a meeting won’t leave a good impression.
Be exact about what the money is for. “Hiring and expansion” tells them nothing. “Two engineers, one sales lead and 15 months of runway to reach ₹10 crore in annual revenue” gives them something to judge.
Keep your company papers, cap table, contracts, financial statements and key agreements together. When investors ask for them, you won’t have to waste time searching through files.
Look at a fund’s past investments before contacting them. If they don’t back businesses like yours, there’s little point in “pitching” to them. You should try to get an introduction from someone they know instead of sending “cold emails”.
What happens after the money arrives?
The cheque clearing feels like a finish line. It’s where expectations begin, and your next raise depends on what you do with this one.
Decide what has to be true in “12 to 18 months” — a revenue number, a customer count or a launch, and hire around it. If a role doesn’t move you toward that, it can wait a quarter.
Check runway every month, even when the balance looks comfortable. Pick your trigger now: when runway falls below “nine months”, you either start raising or start cutting. Deciding in advance keeps panic out of the decision.
Think about “scale” before you spend on it, too. If every new customer needs a new hire, growth will stall. If it only comes through discounts, it won’t last. Make sure a customer is worth what it costs to win before you pour money into expansion. You can also learn from other founders’ experiences with hiring, pricing and timing. The startup news section on Malik Times is a good place to find these stories.
Frequently asked questions
How do I get startup funding in India?
Most founders begin with savings or friends and family, then approach angels or a seed fund once there’s a working product and early customers. With DPIIT recognition, Startup India programmes and approved incubators are another route.
Is the angel tax still applicable to Indian startups?
It was abolished in the “2024 Union Budget”. Confirm the current position with a tax professional before closing a round.
How much equity should a founder give up at seed stage?
Often 15 to 25 percent, though it varies. The terms attached matter as much as the percentage.
How much runway should a startup keep?
After a raise, 12 to 18 months is a sensible target. Many advisors suggest starting the next round while six to nine months remain.
Is venture capital right for every Indian startup?
No. VC funding is better suited to businesses that can grow very large. Others may find it easier to use their own money, take venture debt or borrow against future revenue.
Start with your own numbers
Before you read another article on funding, take last month’s net burn and divide it into your bank balance. Then build the 13-week forecast. Once you know how many months you really have, the questions of how much to raise, from whom and by when get a lot easier to answer.