

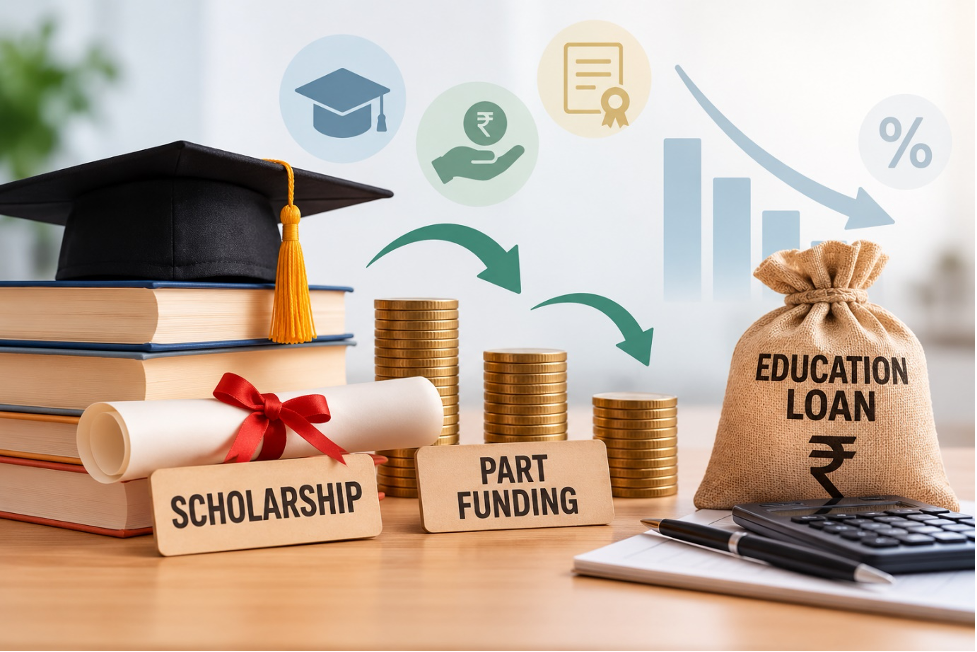
A student who wins a partial scholarship midway through the admission process often wonders whether that money should even be mentioned to the bank, or whether it is simpler to just apply for the full loan and treat the scholarship as a bonus. Mentioning it is almost always the right call.
Lenders build the sanctioned amount around the actual gap between the total cost of the course and whatever the family can cover, and a scholarship or self-funding shifts that gap in ways worth understanding before the paperwork is filed.
Does a Scholarship Actually Reduce the Loan Amount?
In most cases, yes. A bank calculates the loan around the difference between total expenses and the funds already available. So a scholarship covering part of the tuition simply shrinks the amount that needs to be borrowed.
Some lenders ask for a scholarship letter or a fee waiver certificate as proof before adjusting the sanctioned figure, and skipping that disclosure can create complications later if the bank discovers the funding through the fee receipts anyway. There is a practical upside here too.
Borrowing less from the outset means a smaller EMI for the same tenure, or a shorter payoff period if the EMI stays roughly where it would have been without the scholarship. A scholarship that arrives partway through a multi-year course can also be applied against a future year’s disbursement rather than the amount already released.
How Do Lenders Treat Partial Self-Funding?
Self-funding works on the same basic logic, though families sometimes assume it needs to be spent first before the loan gets involved. That is not usually how it plays out. A family contributing, say, a third of the tuition from savings simply reduces what the bank finances, and this contribution can often be phased across the years of a multi-year course rather than paid entirely upfront.
Where things get slightly more complicated is documentation. Banks generally want proof that self-funded contributions are genuinely available, not just promised, so a fixed deposit statement or a savings account with the relevant balance tends to move the process along faster than a verbal assurance.
Families applying for any education loan India often find that presenting this proof early, rather than after the loan committee has already reviewed the file once, avoids a second round of queries.
Where Does Margin Money Fit Into This Picture?
Margin money is the portion of total cost a borrower is expected to fund independently before the loan kicks in, and it is usually waived altogether for smaller loan amounts, commonly cited around ₹4 lakh, while a modest percentage applies above that threshold for courses within India and a somewhat higher one for study abroad.
A scholarship or self-funded contribution can typically be counted toward satisfying this margin requirement, which means securing one before the loan application goes in can sometimes remove the need to arrange separate margin funds altogether.
It is worth asking the lender directly whether a particular scholarship qualifies for this purpose, since practices differ slightly from one bank to the next, and a written confirmation on this point avoids any disagreement once disbursement is underway.
Loan conditions vary by size, typically requiring a margin contribution for amounts over ₹4 lakh and collateral for amounts exceeding ₹7.5 lakh.
Does Any of This Actually Touch the Interest Rate?
Generally not directly. A scholarship reduces the principal borrowed rather than the price charged per rupee of that principal. So the rate quoted on the sanction letter stays the same whether or not scholarship funds are involved.
What does change is the total interest paid over the life of the loan, since interest is calculated on a smaller outstanding balance from day one. Anyone comparing offers should still ask each lender to spell out the applicable education loan interest rate clearly before signing anything, because a lower principal at a high rate can still cost more than a larger loan at a meaningfully lower one.
Is the Scholarship Amount Itself Taxable?
For the most part, no. Scholarships granted specifically to meet the cost of education are exempt from income tax, a position that has held consistently regardless of the amount involved, provided the money is genuinely used toward study-related expenses rather than treated as general income.
This exemption sits separately from any deduction a family might later claim on the loan’s interest once repayment begins, so the two benefits are not mutually exclusive and both can apply to the same student in the same academic year.
Keeping the scholarship letter alongside other loan paperwork also makes it easier to answer questions if a tax assessment ever asks where the funds came from.
Putting the Two Together in Practice
A student juggling a partial scholarship alongside a bank loan is usually better off disclosing every source of funding upfront rather than piecing the picture together after disbursement.
Providing the scholarship letter, the self-funding proof, and the fee structure together in a single application produces a cleaner, faster sanction than submitting a bare-minimum request and updating it midway.
Revisiting the numbers with the branch each time a new scholarship or family contribution comes through, rather than assuming the original sanction automatically adjusts on its own, keeps the loan account accurate throughout the course.
None of this changes how a loan fundamentally works; it simply shifts how much of the total cost actually needs financing. Being upfront about every scholarship and every rupee of self-funding, right from the first branch visit, tends to leave a smaller loan, a lighter EMI, and considerably less interest paid by the time the course wraps up.